Homeowners Insurance
Homeowners Insurance for Truckee, Tahoe & Sierra Homes
Homeowners insurance in Truckee, Tahoe, Donner Lake, Tahoe Donner, Reno, and surrounding Sierra communities is not always straightforward.
Wildfire exposure, roof condition, defensible space, snow load, heating type, wood stoves, decks, property access, rental use, and carrier appetite can all affect whether coverage is available and how it should be structured.
This market moves
Mountain home insurance is shaped by more than the house itself.
Wildfire and access
Carriers may review surrounding vegetation, road access, response distance, defensible space, and wildfire modeling.
Snow and construction costs
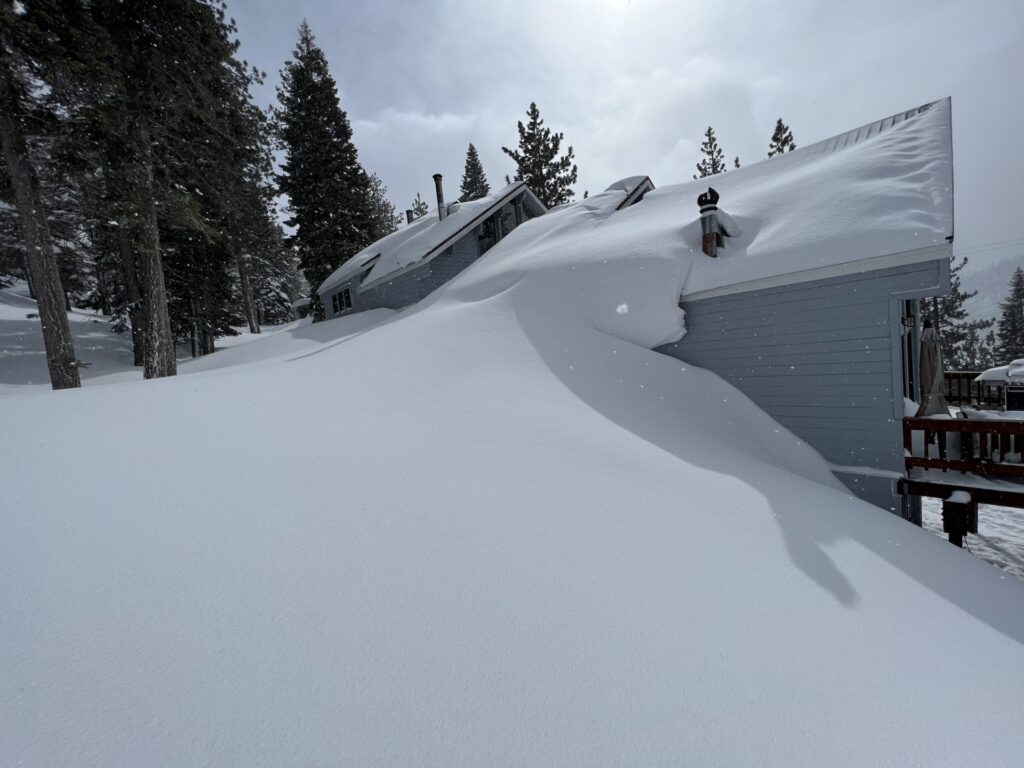
Roof structure, winter conditions, materials, labor availability, and rebuilding costs can affect replacement-cost discussions.
Use and occupancy
Primary homes, second homes, seasonal homes, long-term rentals, and short-term rentals can all be viewed differently.
Coverage paths
The right route depends on the property and the market.
Traditional homeowners markets
When traditional coverage is available, we review fit, coverage structure, replacement cost, deductible options, and timing first.
Specialty or surplus markets
Some homes require non-admitted or specialty placement. These policies can be useful, but the forms and tradeoffs need careful review.
California FAIR Plan + DIC
For some California homes, FAIR Plan coverage may be reviewed alongside separate DIC options. The details matter.
What carriers look at
We help organize the information that matters most.
Property condition
Roof age and material, electrical updates, plumbing, heating systems, and overall maintenance can affect eligibility.
Replacement cost
Living area, construction type, finish level, garages, decks, lower levels, and local rebuilding costs all play a role.
Wildfire mitigation
Defensible space, fire-resistant features, community programs, and documentation can help carriers evaluate the risk.
Occupancy and rental use
Second homes, seasonal homes, long-term rentals, and short-term rentals may each point to different coverage paths.
Claims and timing
Loss history, closing dates, nonrenewal notices, and renewal deadlines can change the practical next step.
Current documents
Declarations, renewal offers, FAIR Plan documents, and replacement-cost estimates can save time and reduce guesswork.
Secondary homes, rentals, and mountain properties
Not every home fits the same homeowners box.
A Truckee cabin used by family, a Tahoe vacation rental, a Reno primary residence, and a landlord property can have different underwriting questions. If a home is rented, even occasionally, the policy should be reviewed carefully so the insurance matches how the property is actually used.
Reviewing the whole household? Explore Personal Auto Insurance alongside your home coverage.
California and Nevada
Two states, different insurance realities.
California properties
California mountain homes may involve admitted markets, non-admitted markets, FAIR Plan options, DIC policies, wildfire underwriting, and evolving carrier rules.
Nevada properties
Homes in Incline Village, Reno, Sparks and Northern Nevada can raise different carrier, wildfire, replacement-cost and liability questions. We keep the state-specific context separate; California FAIR Plan is not a Nevada coverage option.
Request a review
Tell us the basics. We will help with the insurance homework.
If you received a nonrenewal, are buying a home, need lender proof, or are trying to understand FAIR Plan and DIC options, we can help walk through the next step.